
The complete DIY credit repair system
Challenge Every Inaccurate Item on All Three Bureaus. Starting Today.
You audit your own reports. The IF / THEN Guide matches every finding to the exact letter that fits it. Then you challenge all three bureaus at once, not one at a time.
No monthly fees. No waiting around for someone else to do it for you.
Built by an industry insider
I spent ten years inside the credit repair industry, at the two largest companies in it. This is the process they run, the tools they work from, and the insider secrets they would rather you never saw.
Is this for me?
Whatever is on your report, there is already a strategy for it.
This is the first thing everyone wants to know, so let me answer it plainly. You do not need to know anything about credit to use this, and it works for any situation. You have 30 days to see for yourself, or your money back.
Here is how it works. You follow the audit, step by step, and write down what you find. Then you look up what you found in the IF / THEN Strategy Guide. IF this is what you are looking at, THEN this is the letter you send. It is that simple.
You are never left staring at your report wondering what to do next, and you never have to figure out which letter is right, because the Blueprint already worked it out for you. Anyone can follow this. That is the entire point of building it this way.
These are the six that come up most often, and they are usually the ones people give up on. Each one has its own strategy inside the Blueprint and its own customized letters, written to follow the consumer protection laws that apply to that exact situation.
Divorce and joint accounts
A decree says who pays. The bureaus do not read decrees. There is a strategy and a letter for that.
Identity theft and fraud
Federal law gives you specific rights here that almost nobody uses correctly. The letters invoke them properly.
Medical collections
The category with the most reporting errors on it, and specific protections most people never hear about.
Student loans
Servicer transfers create duplicate and conflicting entries constantly. There is a strategy for untangling them.
Bankruptcy
What can and cannot legally remain, and the accounts that are still reporting when they should not be.
Hardship and late payments
Job loss, illness, a rough stretch. There is a documented approach for accounts that went late for a reason.
And if yours is not on that list, you are still covered. The process does not change. You run the audit, you look up what you found, and the Blueprint points you to the letter that fits it.
Try it for 30 days. If it is not for you, email us and we will refund you in full.
No forms and no conditions. You do not have to be sure today. You have thirty days to find out.
The seven steps
How it works
A guided system with a beginning, a middle and an end. You are never doing everything at once, and nobody sets the pace but you.
Set up and protect. Your first 24 hours.
Folder system, ID and proof of address, freeze the invisible bureaus, opt out of pre-screened lists, pull all three reports. Most people finish in under an hour.
Learn the rules, then run the Deep Scan Audit.
How scores are built and which laws protect you, then a full audit across all seven reporting categories on all three reports. You write down what you find. It’s that simple.
Send round one to all three bureaus.
Look up each finding in the IF / THEN Guide, pull the letter it points to, fill in your information and mail it. All three bureaus the same day, so you are working all three at once instead of one at a time.
Build your credit while you wait.
This is the part no monthly service does for you. The bureaus run on their own clock. You do not sit still. Establish new lines, work the three-day window, improve your mix.
Round two and escalation.
Verified does not mean proven. Escalate with the round two Guide, use the variation pivot, and handle reinsertions and date flips.
Round three and the final push.
The stubborn ones. Advanced letters for medical debt, student loans and identity theft, and the paper trail for collectors who will not back down.
Protect what you built.
A ninety day strength plan, the habits that hold a profile in place, and what to do the moment an old item tries to reappear.
How fast you move through this is entirely up to you. There is nobody to wait on and nothing to slow you down. But nothing at all starts happening until the first letters are in the mail, so the sooner you send them, the sooner you get answers back.
What you get
Download it now for just $19.95
A complete step by step system
The Score Nova DIY Credit Repair Blueprint
Nine sections, start to finish. Every step, every letter, every decision, in the order you do them.
Inside the Blueprint, you’ll discover…
The three-day timing move that can change the balance a lender sees, without paying off the debt.
The invisible credit bureaus quietly feeding negative data to the big three, and why freezing them first changes what comes back.
The one-word tweak that shifts the burden of proof and makes a bureau prove the account is even yours.
Why “verified” almost never means proven, and how to turn that response into your strongest round two.
The collection misclassification most debt buyers get wrong, and why that one data field is the softest target on a file.
The escalation pivot that lets you challenge the same account again without getting your file flagged as frivolous.
What to say, word for word, when a phone call gets further in ten minutes than a letter gets in thirty days.
The date discrepancy sitting on millions of files, hiding in plain sight, that almost nobody thinks to challenge.
And that is just a fraction of it.
The 24-Hour Quick Start Guide
Setup, protection and momentum. The seven things to get in place before you write a single letter. Most people finish it in under an hour.
Credit Foundations
The rules of engagement. You do not need to become a credit expert, you need to know the published rules, the fixed deadlines, and what happens when they get missed. Shortest section in the Blueprint, and everything else is built on it.
The Deep Scan Audit
One pass, total visibility. Every error across all three reports, logged in one place. You are not writing letters yet and you are not deciding anything yet. You are a detective at a crime scene: observe and record.
The IF / THEN Strategy Guide
The decision engine. Look up what you found and it tells you the exact letter to send. No judgment calls, no guessing, no wondering whether you picked the wrong one.
Preparing & Sending Round 1 Letters
Where the plan becomes reality. This is the point where most people stall out. Exactly how to prepare, address and mail your letters so they land correctly and count.
The Credit Optimization System
Building and establishing credit while you wait. What no monthly service will ever teach you, because there is nothing in it for them.
Round Two Results & Escalation
What to do when the bureaus respond, stall, or play games. A verified response is not a loss, it is a data point, and this section shows you how to read it and what to send next.
The Final Push
Advanced escalation and how to finish what you started. The stubborn items, the paper trail that makes weak verification collapse, and the letters for medical debt, student loans and identity theft.
Real Proof, Real Progress
Protecting what you built. The ninety day plan, the habits that hold a profile in place, and what to do the moment an old item tries to reappear.
These are not bonuses. These are the two tools the professionals actually work from, and they are the reason a three-bureau dispute stays organized instead of turning into a pile of paper on the kitchen table.
The Credit Repair Command Center
Thirteen tabs. Every item, every bureau, every mail date, every response, every deadline, in one place. Open it and you know exactly where you stand.
The Insider Dispute Letter Library
32 letters, written and ready to send. Round one, round two, escalation, and the customized ones for divorce, identity theft, medical, student loans, bankruptcy and hardship.
These are the things I learned inside the industry that nobody puts in an ad. They do not make the Blueprint longer or more complicated. They are what you reach for when your situation calls for one. Included free.
Utilization Playbook
Two levers the monthly services almost never bother with, because neither one bills a client. How to time a payment around your statement date, and how to spread balances instead of leaving one card sitting near its limit. Neither requires paying the debt down.
DOLA Discrepancy Strategy
My favorite one. When three bureaus report three different dates on the same account, they are contradicting each other in writing. Almost nobody notices it. You will know exactly where to look and what to do with it.
Insider Phone Scripts Pack
What the people on the other end of the line actually respond to. Word for word, what to say and what to never say, for the moments a call beats a letter.
Credit Repair Case Study Walkthroughs
Real files, worked start to finish, so you can find the one that looks like yours and see exactly how it was handled.
Plus free lifetime updates, forever, at no extra cost.
One-time purchase. Yours to keep. 30-day money-back guarantee.
Instant download · 6 free tools and bonus guides · Free lifetime updates
The math
You are not paying someone to do the work. You are paying for the process they would have run.
A monthly credit repair service bills you every month. That is the whole business model, and it shapes everything they do. A few disputes go out. Everyone waits. A few more go out next cycle, everyone waits again. Not because that is the fastest way to work a file, but because the longer they take, the more you pay. Six months of that is $839.70, and at the end of it you own nothing.
Doing this yourself is not hard. It is just unfamiliar. That is the only thing they were ever really selling you, and it is the entire reason this costs $19.95 once instead of $139.95 a month.
$139.95 per month is the current published price of a leading national credit repair service, not a Score Nova price.
See the tools
Look inside before you buy
No mystery about what you are getting. This is what the tools actually look like in use.
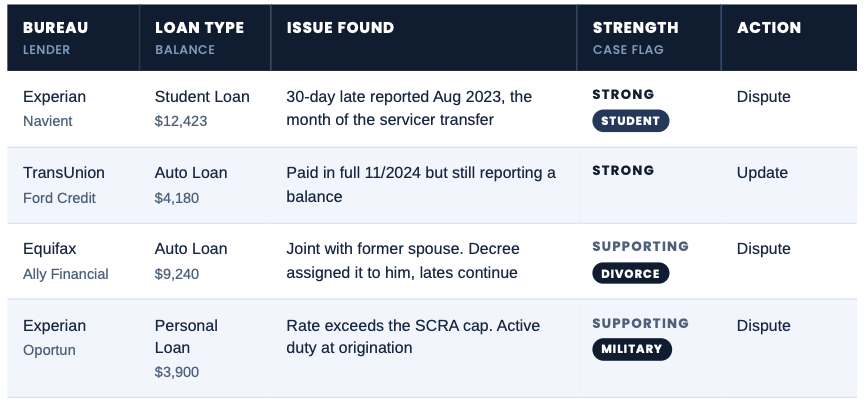
Every error, every bureau, one sheet. This is what a finished audit looks like before a single letter goes out.
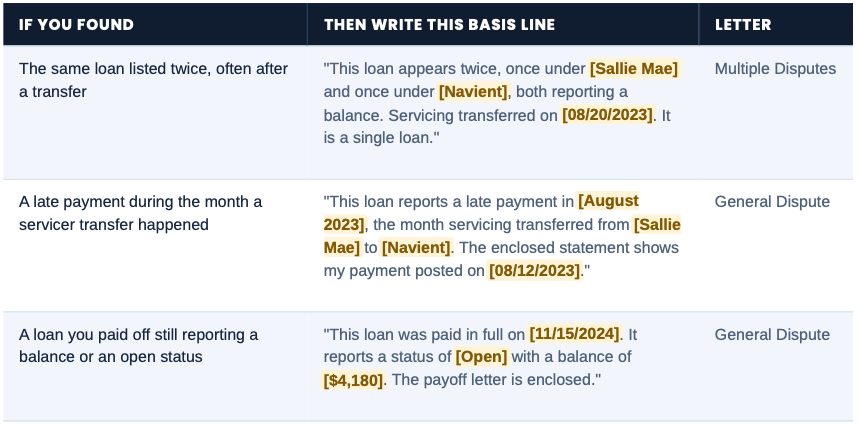
This is the part that removes the guesswork. What you found is on the left. The letter you send is on the right. That is the whole decision.
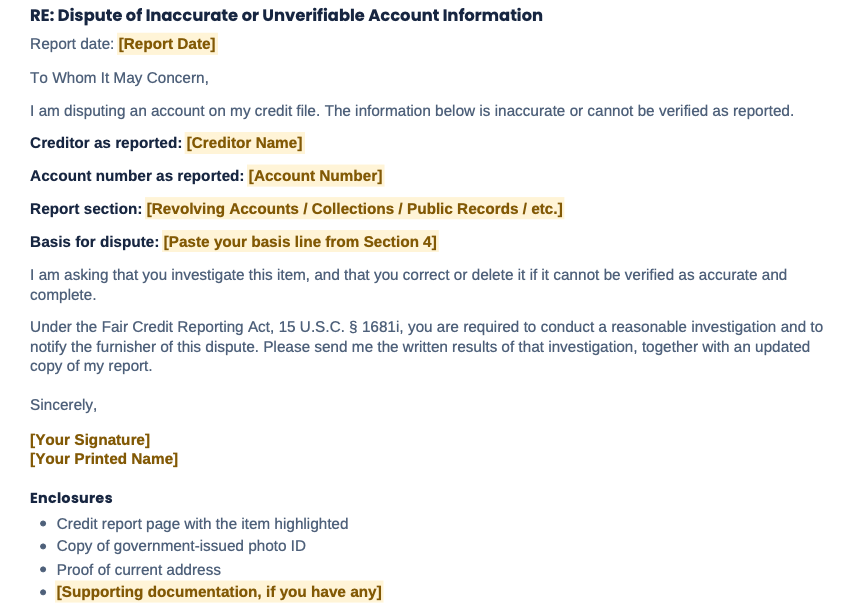
The wording is already written. You fill in the gold and mail it. No legal drafting, no wondering whether you said the wrong thing.
The truth about the ads
Nobody can promise you a number. Anyone who does is lying to you.
You have seen the ads. Raise your score 100 points. Results in 30 days. Guaranteed deletions.
Ten years inside this industry taught me exactly what those promises are worth. Nothing. Nobody controls what a bureau decides, and every company advertising a number knows it.
Here is what they will never tell you: they are not better at this than you are about to be. They are running a process. That process is what you are about to download.
What actually shapes the outcome is what is on your reports, what you can document, and how consistently you follow through. That is true whether you do it yourself or pay someone every month. The difference is that here you see exactly what is happening at every step, and nobody is billing you while you wait.
Built by an industry insider

“I spent ten years inside the credit repair industry. Now I’m giving away the process.”
For ten years I worked inside the credit repair industry. My team drove growth for CreditRepair.com and Lexington Law, the two largest companies in the space. I watched what the process actually is, and I watched what people paid for it month after month.
There is no secret in there. There is a process, and a lot of people charging a monthly fee to keep it behind a curtain. So I wrote it all down and priced it at what it costs me to hand it to you.
What waiting actually costs
Every month you wait, bad credit takes money out of your pocket.
Higher interest on the car payment. A bigger deposit on the apartment. The loan that comes back declined. That is not a feeling, it is a number, and you pay it again every month the report stays the way it is.
And the bureaus get thirty days to answer each round. So if you want your report in better shape by spring, the letters need to go out now, not in the spring.
Try it for 30 days. If it is not for you, email us and we will refund you in full.
Twenty dollars to find out, and thirty days to change your mind. Waiting costs you more than trying.
One-time purchase. Yours to keep. Instant download.
Instant download · 6 free tools and bonus guides · Free lifetime updates
Still wondering
Questions
Will this work for my situation?
The process is the same no matter what is on your file. What changes is which letter you send, and the Library already holds the customized ones for the hard cases: identity theft, divorce accounts, medical debt, student loans, bankruptcy and hardship. You run the audit, the IF / THEN Guide points you at the right letter. What comes back depends on what is actually in your file and how consistently you follow through.
What if I am not good at this kind of thing?
Then start with the free 24-Hour Quick Start Guide. It is seven setup tasks and most people finish it in under an hour. If you can do those seven things, you can do the rest of this, because the rest is the same kind of work with the decisions already made for you.
Is this a credit repair service?
No. Score Nova is a self-help educational system. You audit your own reports and you mail your own letters under your own signature. Nobody here contacts a bureau, a creditor or a collector on your behalf.
How long does this take?
Your part can move as fast as you want. Setup takes about an hour and round one can go out the same day. After that you are waiting on the bureaus, and federal law gives them thirty days from receipt to complete an investigation. What comes back, and how many rounds it takes, depends on your file.
Is this legal?
Yes. Challenging inaccurate or unverifiable information on your own credit report is a right you already have under federal law. This shows you how to use it properly, including when not to dispute something, because challenging accurate data is how people get a whole file flagged as frivolous.
What if I buy it and it is not for me?
Email us within 30 days and we will refund you in full. No forms, no conditions.
Free, no purchase needed
Want to try before you buy? Go for it! Download the 24-Hour Quick Start Guide for free.
Seven setup tasks, the Blueprint introduction, and the full table of contents. It is Section 1 of the Blueprint, and we will send it to you free.
If you can do the seven things in that guide, you can do the rest of this. That is the whole test.
Or skip the free guide and start with the whole system today.
One-time purchase. Yours to keep. 30-day money-back guarantee.
Questions at any point, email [email protected]
Score Nova is a self-help educational system, not a credit repair service. You audit your own reports and mail your own letters under your own signature. Results depend on what is in your file and the work you do.
Copyrights 2026 | Score Nova™ | Terms & Conditions | Privacy Policy